


FORT WORTH, Texas — American Airlines Group Inc. (NASDAQ: AAL) today reported its third-quarter 2026 financial results, reflecting execution of its commercial strategy and the benefits of long-term investments in its customers, team members, network, fleet and technology.
Third-quarter financial highlights:
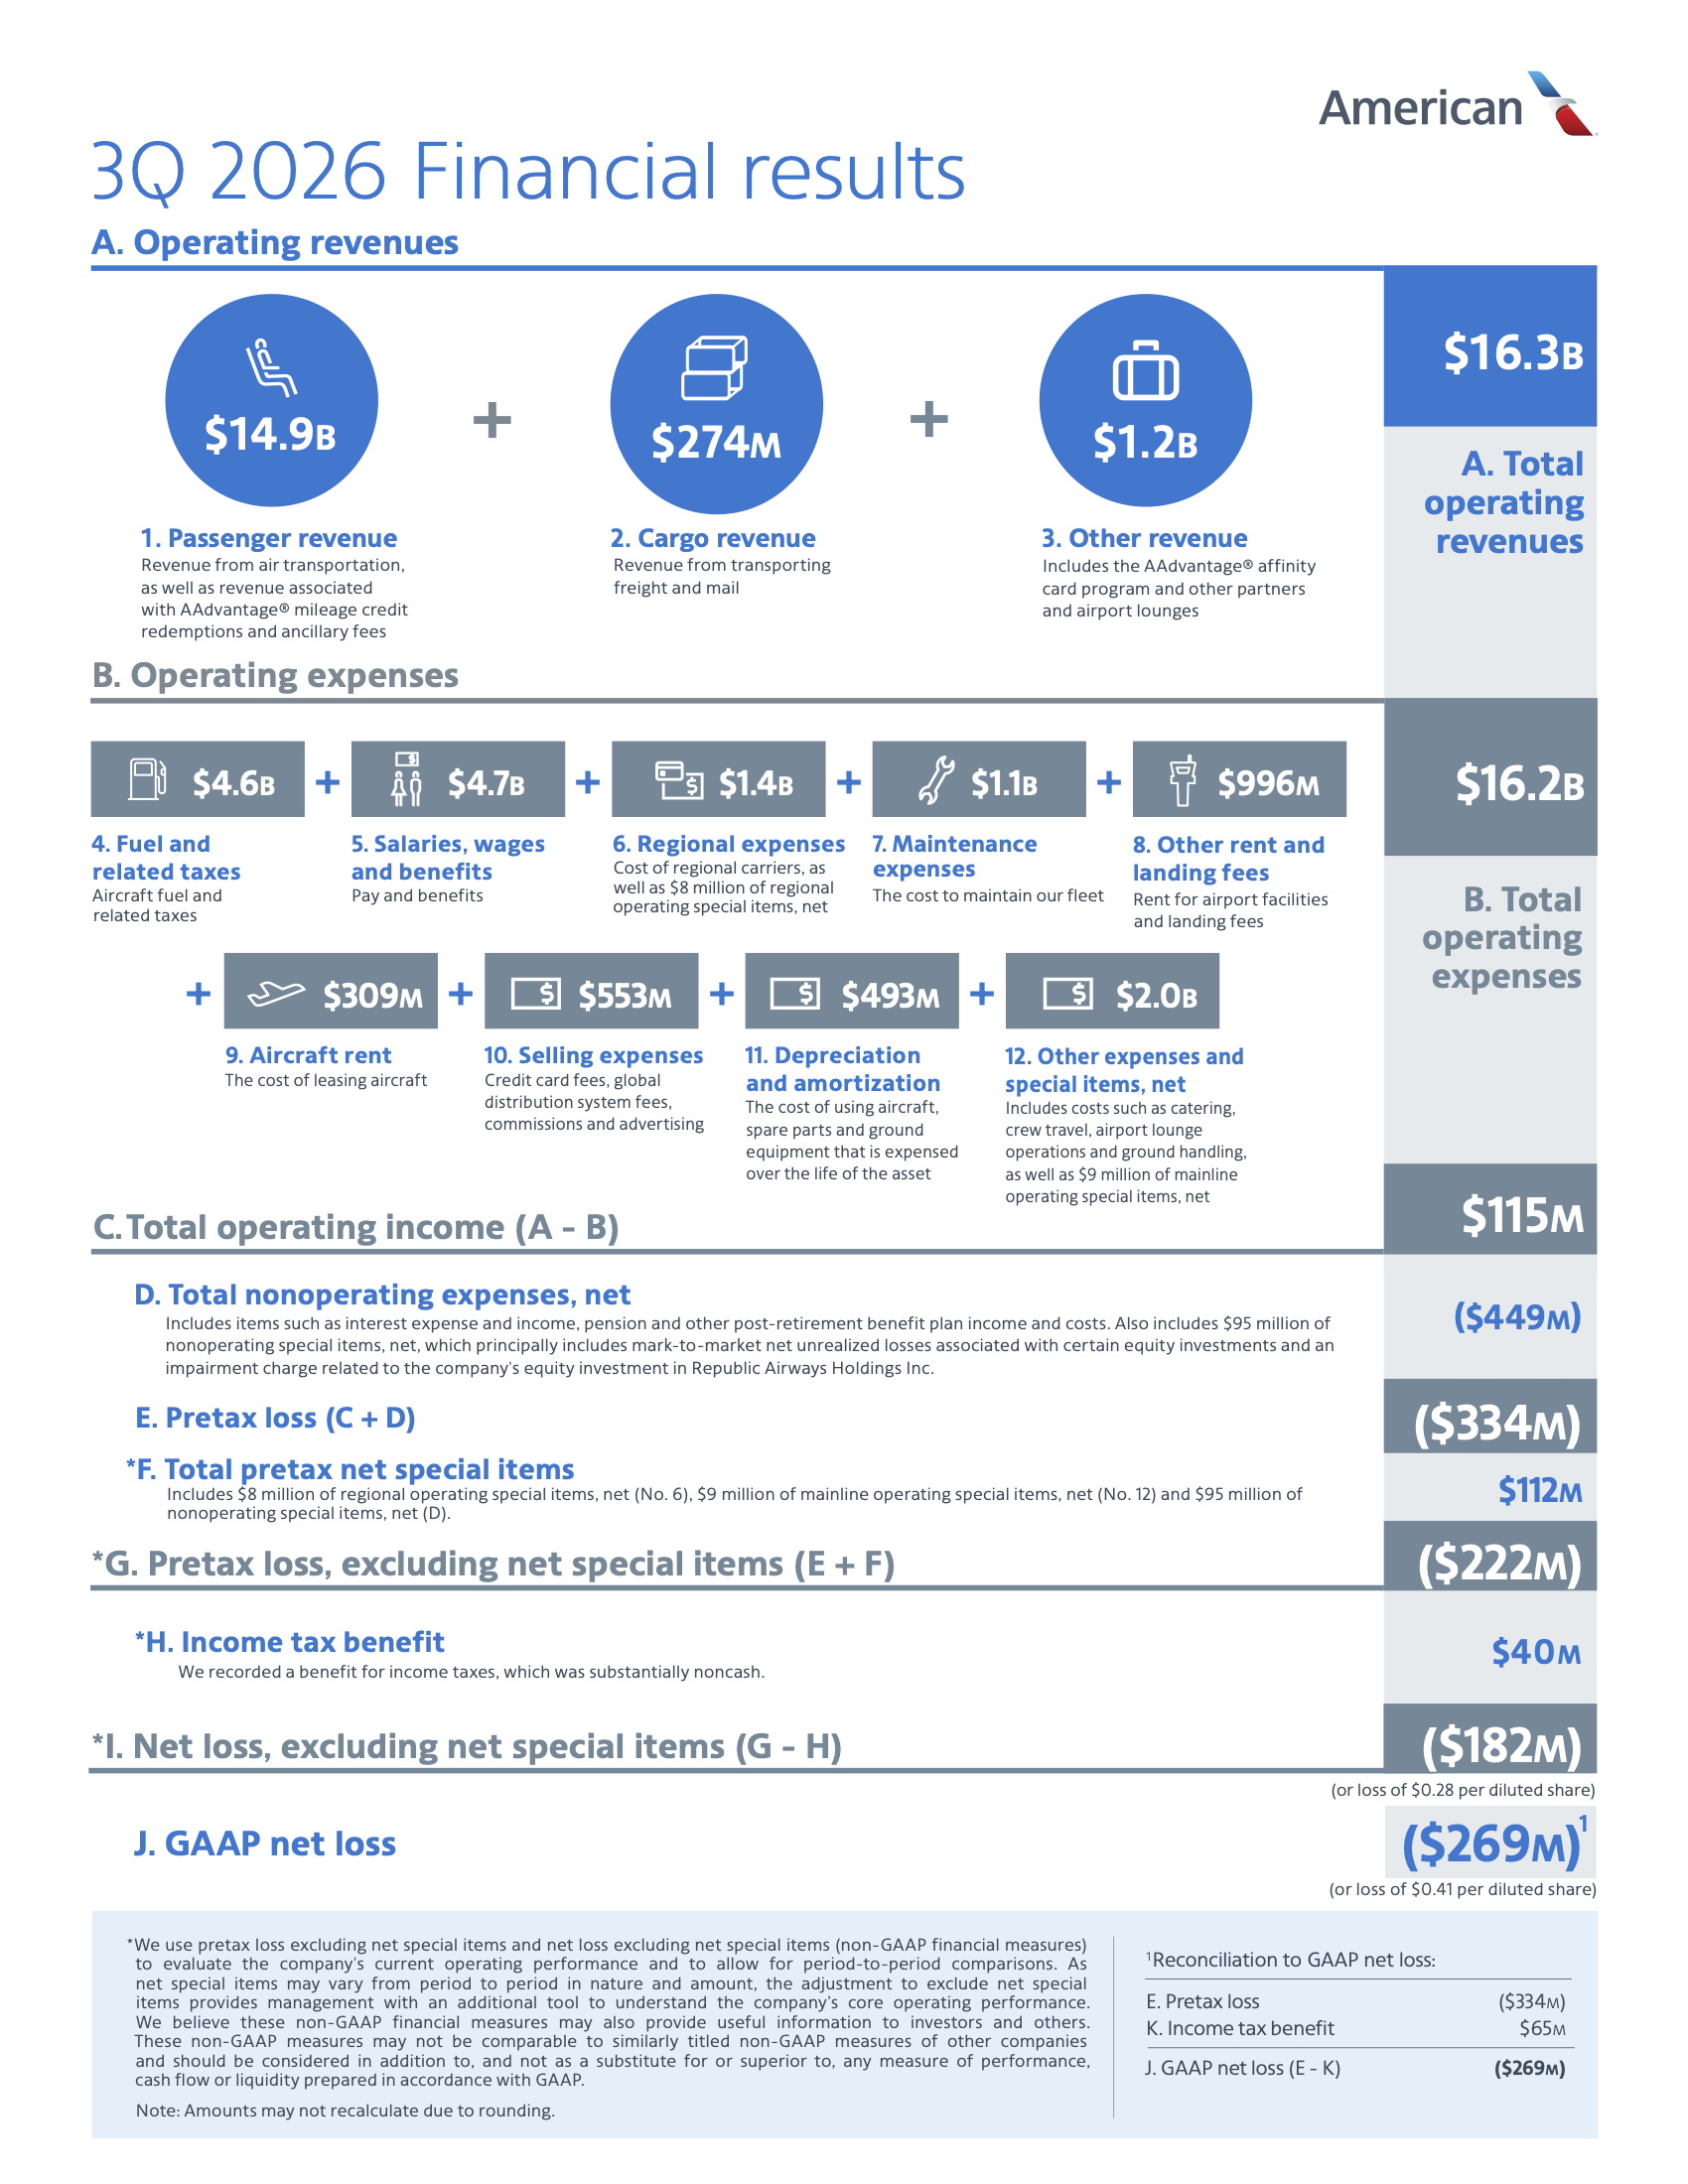
- Total revenue of $16.3 billion, up 19.3% year over year, above the high end of the previously announced guidance range.
- Delivered the best unit cost performance among the network carriers, with CASM-ex1 up 3.0%.
- Fuel expense for the quarter increased $1.9 billion, or 67.5%, year over year.
- GAAP net loss of $269 million, or ($0.41) per diluted share.
- Adjusted net loss of $182 million2, or ($0.28) per diluted share. Adjusted net loss was only $71 million below third quarter 2025 despite the $1.9 billion increase in fuel expense.
Resources
“American delivered record third-quarter revenue and the strongest year-over-year revenue growth in my career, with premium performance leading the way,” said American's CEO Robert Isom. “The investments we are making across the four pillars of our commercial strategy are working, and we expect another quarter of record revenue growth to close out the year. While historically high fuel prices significantly impacted our financial results, our focus remains on restoring profitability and building a stronger American for the long term. I’m grateful to the American Airlines team for making this progress possible.”
The company’s third-quarter results were driven by strong revenue performance across all geographies and cabins:
- Premium revenue increased 22.9%, and Main Cabin revenue increased 19.5% year over year.
- Total unit revenue increased 14.5% year over year, reflecting continued strength in demand for travel.
- Domestic passenger unit revenue increased 13.6% year over year in the third quarter.
- International passenger unit revenue increased 16.4%, with the Latin America entity up 21.1%, the Atlantic entity up 14.5% and the Pacific entity up 11.3% compared to the third quarter of 2025.
- AAdvantage® enrollments increased 27.4% year over year.
- Demand for business travel remained strong, with managed corporate revenue increasing 27.6% year over year, marking the sixth consecutive quarter of double-digit growth.
This revenue performance was a result of the company’s continued focus on its four commercial pillars: elevate the customer experience, grow the global network, drive premium revenue and lead in loyalty.
1) Elevate the customer experience
American’s investments in high-speed connectivity, lounges, seatback entertainment, airport facilities and fleet modernization are creating the foundation for a best-in-class customer experience.
In May, American announced plans to equip more than 500 aircraft with high-speed Starlink Wi-Fi, representing the largest in-flight connectivity upgrade in the airline’s history. Building on that commitment, the company announced on Oct. 8 that it plans to expand Starlink installation across its entire mainline fleet, bringing the technology to more than 1,000 aircraft. Once installation is complete, American will offer one of the largest fleets of Starlink-connected aircraft in the world.
The company also continues to grow its Admirals Club® and premium lounge network with more lounges opening or being renovated than at any point in company history. Additionally, American announced the expansion of seatback entertainment to the narrowbody fleet, including screens on new deliveries beginning in 2028. With these foundational investments underway, American remains focused on further improving customer satisfaction through enhanced operational reliability, better disruption management and a more consistent travel experience.
2) Grow the global network
American continues to strengthen its global network, offering customers more destinations, better connectivity and greater schedule utility. At Dallas Fort Worth International Airport (DFW), this year's rebank produced record passenger volumes, fewer misconnections and mishandled bags, and unit revenue that outpaced the rest of the system. In Chicago, Miami, Philadelphia and Phoenix, American is building stronger schedules for local customers.
3) Drive premium revenue
American continues to see momentum in premium demand, demonstrating the benefits of recent investments across its premium products and customer experience. Premium passenger unit revenue increased 18.5% year over year during the third quarter, compared with an increase of 14.4% in Main Cabin.
American plans to continue expanding premium seating through the delivery of new aircraft and the retrofit of existing aircraft. Premium products generate roughly half of the company's ticket revenue on approximately 30% of seats today. Through the recently announced narrowbody retrofit program, American expects premium seats on narrowbody aircraft to increase to 40% in the coming years.
The company also continues to take actions to improve revenue quality and provide customers with a broader range of choices. These initiatives contributed to a 6-point increase in the upsell rate from Basic Economy to Main Cabin during the quarter.
4) Lead in loyalty
The AAdvantage® program remains one of American's strongest competitive advantages, driving customer engagement, premium demand and long-term value creation. The program continues to benefit from strong member activity, increased engagement and enhancements to American’s co-branded credit card program.
Enrollments in the AAdvantage® program increased 27.4% year over year in the third quarter. American’s co-branded credit card partnership with Citi saw year-over-year third-quarter card spend growth of nearly 10%.
Efficiency and cost performance
American continues to benefit from long-term investments in technology, procurement and other initiatives designed to build a more efficient and resilient airline. The company is reengineering how work gets done across the business, improving productivity and simplifying processes while continuing to invest in the customer and team member experience.
By the end of 2026, the company expects to have achieved nearly $1 billion in annual run rate savings and more than $900 million in working capital improvements through its multiyear reengineering efforts. American continues to identify opportunities to use technology, automation and artificial intelligence to simplify the business and equip team members with better tools to improve decision-making.
“We remain focused on the factors that drive the most value,” said American’s Chief Financial Officer Devon May. “Our long-term focus on efficiency supported industry-leading unit cost results in the quarter, with CASM-ex increasing 3.0% year over year. For the full year, we expect to lead the network carriers in the spread between year-over-year unit revenue and CASM-ex growth.”
Overall financial results were pressured by a significant increase in fuel costs. American paid an average of $3.85 per gallon in the third quarter, which increased fuel expense by $1.9 billion year over year.
Balance sheet and liquidity
American ended the third quarter with $11.8 billion of total available liquidity and more than $26 billion of unencumbered assets and first-lien capacity. The company remains committed to reducing debt, lowering interest expense and achieving its target of 3.0x net debt3 to EBITDAR, in line with BB credit metrics.
Outlook and financial guidance
In the fourth quarter, the company expects continued revenue strength, with year-over-year revenue growth between 19.5% and 22.5%. Based on the forward fuel curve as of Oct. 19, American anticipates an average fuel price of approximately $4.70 per gallon, nearly double the price paid in the fourth quarter of 2025. At that price, fuel expense is expected to increase approximately $2.8 billion versus the fourth quarter of 2025.
Given elevated fuel prices, American expects network growth in 2027 to slow from 2026 levels.
| FY 2026E | |
|---|---|
| Adjusted loss per diluted share4 | ($1.60) – ($1.00) |
Conference call and webcast
American will host a conference call at 7:30 a.m. CT today. A live webcast and replay will be available at American’s investor relations website.
Notes
See the accompanying notes in the financial tables section of this news release for further explanation, including reconciliations of certain GAAP to non-GAAP financial information.
- Cost per available seat mile excluding net special items, fuel and profit sharing, or CASM-ex, is a non-GAAP measure. The company is unable to reconcile certain forward-looking information to GAAP because the nature or amount of net special items cannot be determined at this time.
- Adjusted net loss is a non-GAAP financial measure and excludes $87 million of net special items after the effect of taxes that the company recognized in the third quarter.
- Net debt includes debt, finance and operating lease liabilities and pension obligations less unrestricted cash and short-term investments.
- Adjusted loss per diluted share guidance excludes the impact of net special items and represents an absolute number, not a year-over-year comparison. The company is unable to reconcile certain forward-looking information to GAAP as the nature or amount of net special items cannot be determined at this time.
Financial results
Click the button below to download the third-quarter 2026 financial results.